The gap between what Europeans earn and what it costs to buy a flat or a house is widening, fuelling a crisis that threatens to spill beyond the housing market.
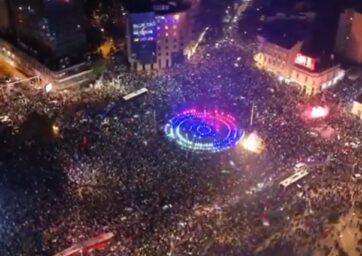
In Spain, frustration over unaffordable housing erupted this week into one of the biggest protests in recent years. Around four million workers took part in a nationwide general strike, according to trade unions. It was the first of its kind in 14 years. Thousands took to the streets of Madrid, Barcelona and other cities.
Most demonstrations remained peaceful, but clashes with police broke out in some places later in the evening. Rubbish bins were set alight and protesters threw objects at officers.
Spain faces a particularly acute shortage. According to the country’s central bank, it lacks around 750,000 homes. Meanwhile, rising rents are putting growing pressure on households priced out of homeownership.
You might be interested
Events in Spain offer a stark illustration of how urgent housing affordability has become. But the problem extends far beyond one country. The latest Eurostat figures show that the relationship between property prices and household incomes has deteriorated across the EU over the past decade. In 2025, the ratio stood 6.8 per cent higher than in 2015.
The picture varies considerably across member states. The price-to-income ratio rose in 17 EU countries over the decade, while it fell in ten others. Portugal recorded the sharpest deterioration, with the ratio climbing by 60.8 per cent. The Netherlands followed at 34.3 per cent, Hungary at 26.5 per cent, Czechia at 25.8 per cent and Spain at 24.5 per cent.
At the other end of the scale, Romania saw the ratio fall by 42.8 per cent. Finland (-25.2 per cent) and Bulgaria (-16.2 per cent) also recorded substantial improvements.
A combination of economic growth, insufficient construction, demographic shifts and rising demand for property as an investment helps explain these differences across Europe.
The ranking does not, however, show where housing is most expensive. It measures how affordability has changed relative to household incomes in each country. A falling ratio does not automatically mean homes are cheaper or more affordable than in countries where the figure has risen.
Why are some countries doing better than others?
One important factor is how quickly household incomes grow. Over recent decades, several formerly low-income economies in Central and Eastern Europe have gradually caught up with wealthier Western European countries. Faster income growth helped offset rising property prices in some of them.
In its housing market analysis last year, the European Commission highlighted countries such as Romania, Bulgaria, Poland and Lithuania. Household incomes in these countries grew substantially over the longer term. This helped improve their price-to-income ratios, even as property prices continued to rise.
Other countries have seen property prices pull further and further away from household incomes. Portugal is a striking example. The European Commission estimates that Portuguese property was around 35 per cent overvalued at the end of 2024. Portugal also ranks among the countries where tourism has had a particularly strong impact on house prices.
Tourists and investors squeeze out locals
In popular tourist destinations, local residents are no longer the only ones competing for property. Foreign buyers, investors and second-home owners add to demand. The growth of short-term rentals is also changing how people use housing.
Landlords may favour tourists over long-term tenants when holiday lets offer higher returns. This shifts some properties away from the conventional rental market, leaving fewer homes available to local residents.
Urbanisation and migration create further pressure. People move to economically prosperous cities in search of jobs and services. Yet construction often fails to keep pace with their growing populations. Changes in household composition add to the strain. More people now live alone, creating demand for more separate homes than in the past.
New homes are not being built fast enough
Rising demand would not necessarily drive prices so sharply upwards if supply kept pace. But Europe’s housing market has struggled on this front for years. New home construction has failed to meet demand over the past decade, with building activity remaining at historically low levels. This is also borne out by a European Central Bank analysis published in May 2026, which found that housing supply had failed to keep pace with rising demand in several countries.
Several obstacles stand in the way. Building land is scarce and expensive in desirable locations. Complex planning rules and lengthy permit procedures also delay construction. Meanwhile, the building sector faces labour shortages and low productivity.
Another complication is the shift in housing investment away from new construction towards renovating existing buildings. More money now goes into energy upgrades and modernisation to meet current standards and new legislation.
Higher mortgage costs put homes out of reach
Slower property price growth does not automatically make buying a home more affordable. For most people, the purchase price is only part of the equation. The cost of financing a property matters just as much.
Interest rate rises since 2022 have made mortgages significantly more expensive. They have also reduced how much households can borrow. The European Commission estimates that mortgage borrowing capacity in 2024 was lower than in 2019 in 12 member states. In the remaining countries, it increased, largely thanks to income growth.
Even so, between 2019 and 2024, house prices outpaced the growth in household borrowing capacity in almost every member state. Bulgaria, Romania and Malta were the exceptions.
The housing crisis affects renters as well as buyers
Rising property prices and more expensive mortgages also affect people who may never buy a home. For them, the availability of rental housing and the cost of monthly payments matter most.
Property prices across the EU rose by 53 per cent between 2010 and 2024. Rents increased by 25 per cent over the same period. In 2024, the average EU household spent 19 per cent of its disposable income on housing. For households earning less than 60 per cent of their country’s median income, the figure reached 37 per cent.
Once again, differences between countries are substantial. Housing accounted for the largest share of household income in Greece, at 36 per cent. Denmark followed at 26 per cent, while Sweden and Germany both stood at 25 per cent. At the other end of the scale, Cyprus recorded the lowest share, at just 11 per cent. Italy and Slovenia also stood well below the EU average of 19 per cent, at around 14 per cent.
In 2025, 7.7 per cent of the EU population lived in households spending at least 40 per cent of their disposable income on housing. The problem was more pronounced in cities than in rural areas.
Europe’s housing affordability problems have no single cause, and therefore no simple solution. Tackling them will require different approaches to the pressures facing each country’s housing market, from insufficient construction to investment demand and rising borrowing costs.